
REVERSE MORTGAGE SPECIALIST
See How Your Home Equity Could Help Support Your Retirement
If you're 62 or older, a reverse mortgage may allow you to access a portion of your home's equity while continuing to own your home.
Get Your Personalized
Reverse Mortgage Estimate
Complete the short form and I'll contact you to discuss your options.
By submitting this form, you acknowledge that the information you provide will be used to respond to your inquiry. Privacy Policy
Licensed California
Loan Originator
NMLS #1297562
Personal One-on-One
Guidance
No call center. Work directly with Bryce.
Straightforward
Information
Clear answers so you can make an informed decision.
What Could a Reverse Mortgage Do for You?
For eligible homeowners, a reverse mortgage can provide access to home equity without requiring monthly principal and interest mortgage payments.
Pay off an existing mortgage
Supplement retirement income
Establish a line of credit
Pay for home improvements
Cover unexpected expenses
Provide additional financial flexibility during retirement
How Does a Reverse Mortgage Work?
Determine Eligibility
You must be at least 62 years old and meet program requirements. I will help you determine eligibility.
1.
Access Your Equity
Depending on your circumstances, proceeds may be available through a lump sum, line of credit, monthly payments, or a combination.
2.
No Required Loan Payment
You will not be required to pay principal & interest. Property taxes and insurance expenses may be rolled into loan in certain cases.
3.
The Loan is Repaid Later
The loan generally becomes due when the last borrower permanently leaves the home, sells the home, or another maturity event occurs.
4.
Common Reverse Mortgage Questions
-
Yes, you maintain ownership of your home. As with other mortgages, you must continue to meet the requirements of the loan.
-
Reverse mortgages generally do not require monthly principal and interest payments. You remain responsible for property taxes, insurance, maintenance and other applicable expenses. In some cases the taxes and insurance can be paid by the reverse mortgage.
-
Having a mortgage already does not prevent you from getting a reverse mortgage. Most commonly people will payoff their current mortgage with the new reverse mortgage. In some cases a reverse mortgage can can be added in addition to the current mortgage.
-
The amount available depends on factors including the age of the youngest eligible borrower, home value, current interest rates, existing liens, and the reverse-mortgage program.
-
The reverse mortgage balance will become due at the time of sale. The balance will be paid with the proceeds from the sale. Once the loan is paid off and applicable sales costs are paid, the remaining equity belongs to you.
-
Generally your heirs or beneficiaries will need to payoff the mortgage by either selling the property or refinancing the reverse mortgage to a mortgage in the heir’s name.
-
Yes, similar to traditional mortgages there will be costs that can include: lender origination charges, appraisal fees, title and escrow fees, and FHA mortgage insurance premiums. Often times the closing costs are paid by the loan rather than out of pocket.
-
No. Your financial situation, goals, housing plans, available equity and alternatives should all be considered. I'll help you understand the numbers and available options so you can make an informed decision.
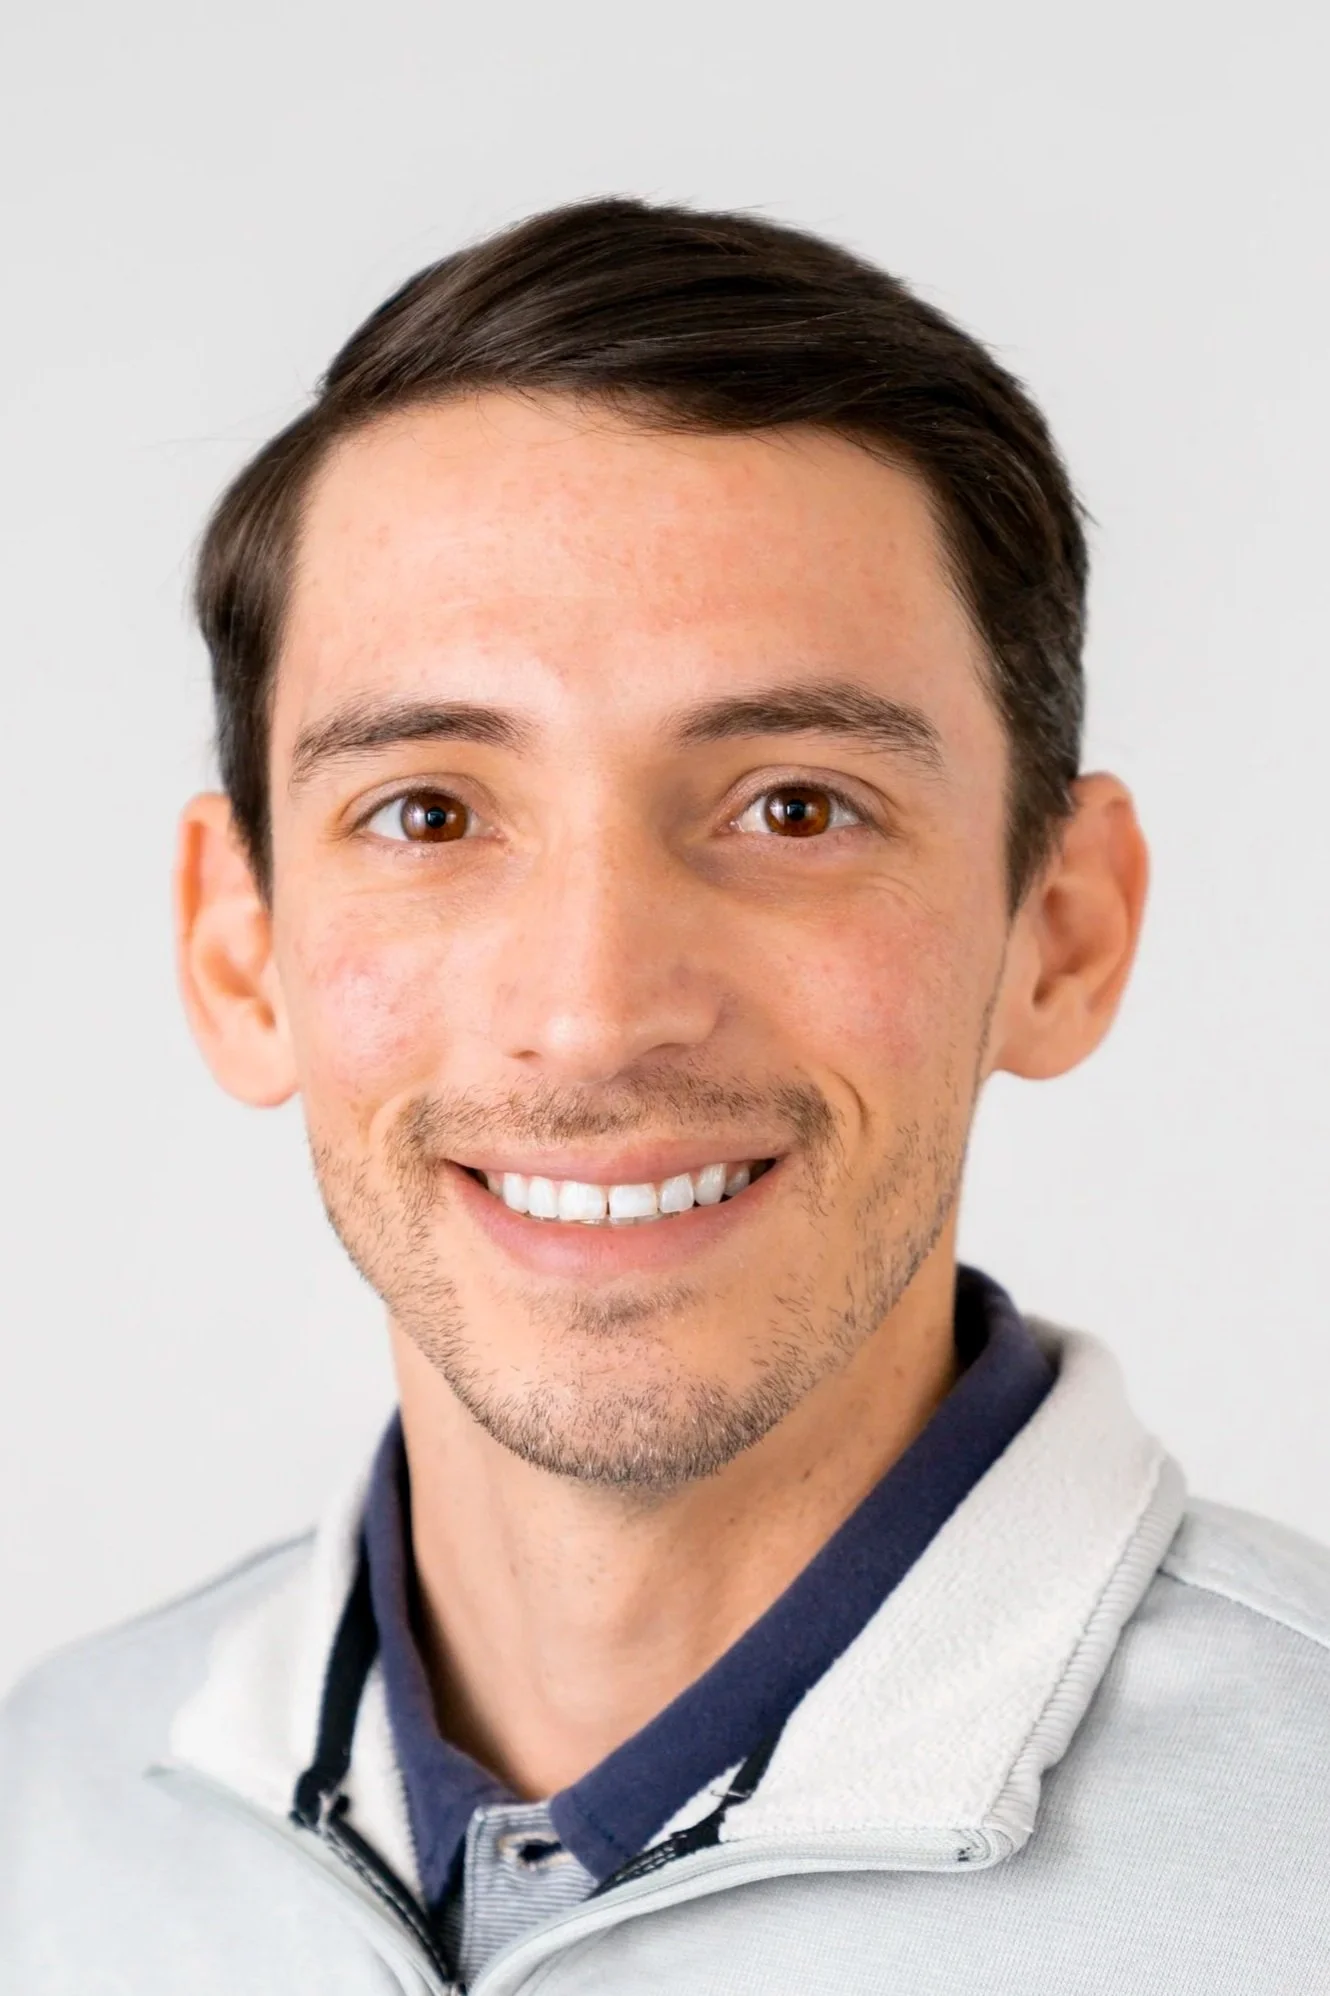
Bryce Padilla
Loan Originator
NMLS #1297562
I'm Bryce Padilla, a licensed mortgage loan originator with Loan Advisor Group. I'll personally help you understand how a reverse mortgage works, what options may be available based on your situation, and what the costs and responsibilities would be.
You'll have an opportunity to ask questions before deciding whether you'd like to move forward.
Have Questions?
Let’s Talk.
Prefer to Talk? 626-609-7650
A reverse mortgage is a loan. Interest and applicable fees are added to the loan balance over time, which generally reduces the equity remaining in the home.
Borrowers must continue to meet the requirements of the loan, including paying property taxes and homeowners insurance, maintaining the property, and paying other applicable property charges. Failure to meet these obligations may cause the loan to become due and payable.
The loan generally becomes due and payable when the last borrower sells the home, permanently leaves the home, passes away, or another maturity event occurs.
For FHA-insured Home Equity Conversion Mortgages (HECMs), borrowers must complete counseling with an approved housing counselor before obtaining the loan.
This is not a commitment to lend. All loans are subject to applicable program requirements, borrower and property eligibility, underwriting, and other conditions.
This website is not affiliated with or acting on behalf of the U.S. government, HUD, FHA, or any other government agency.